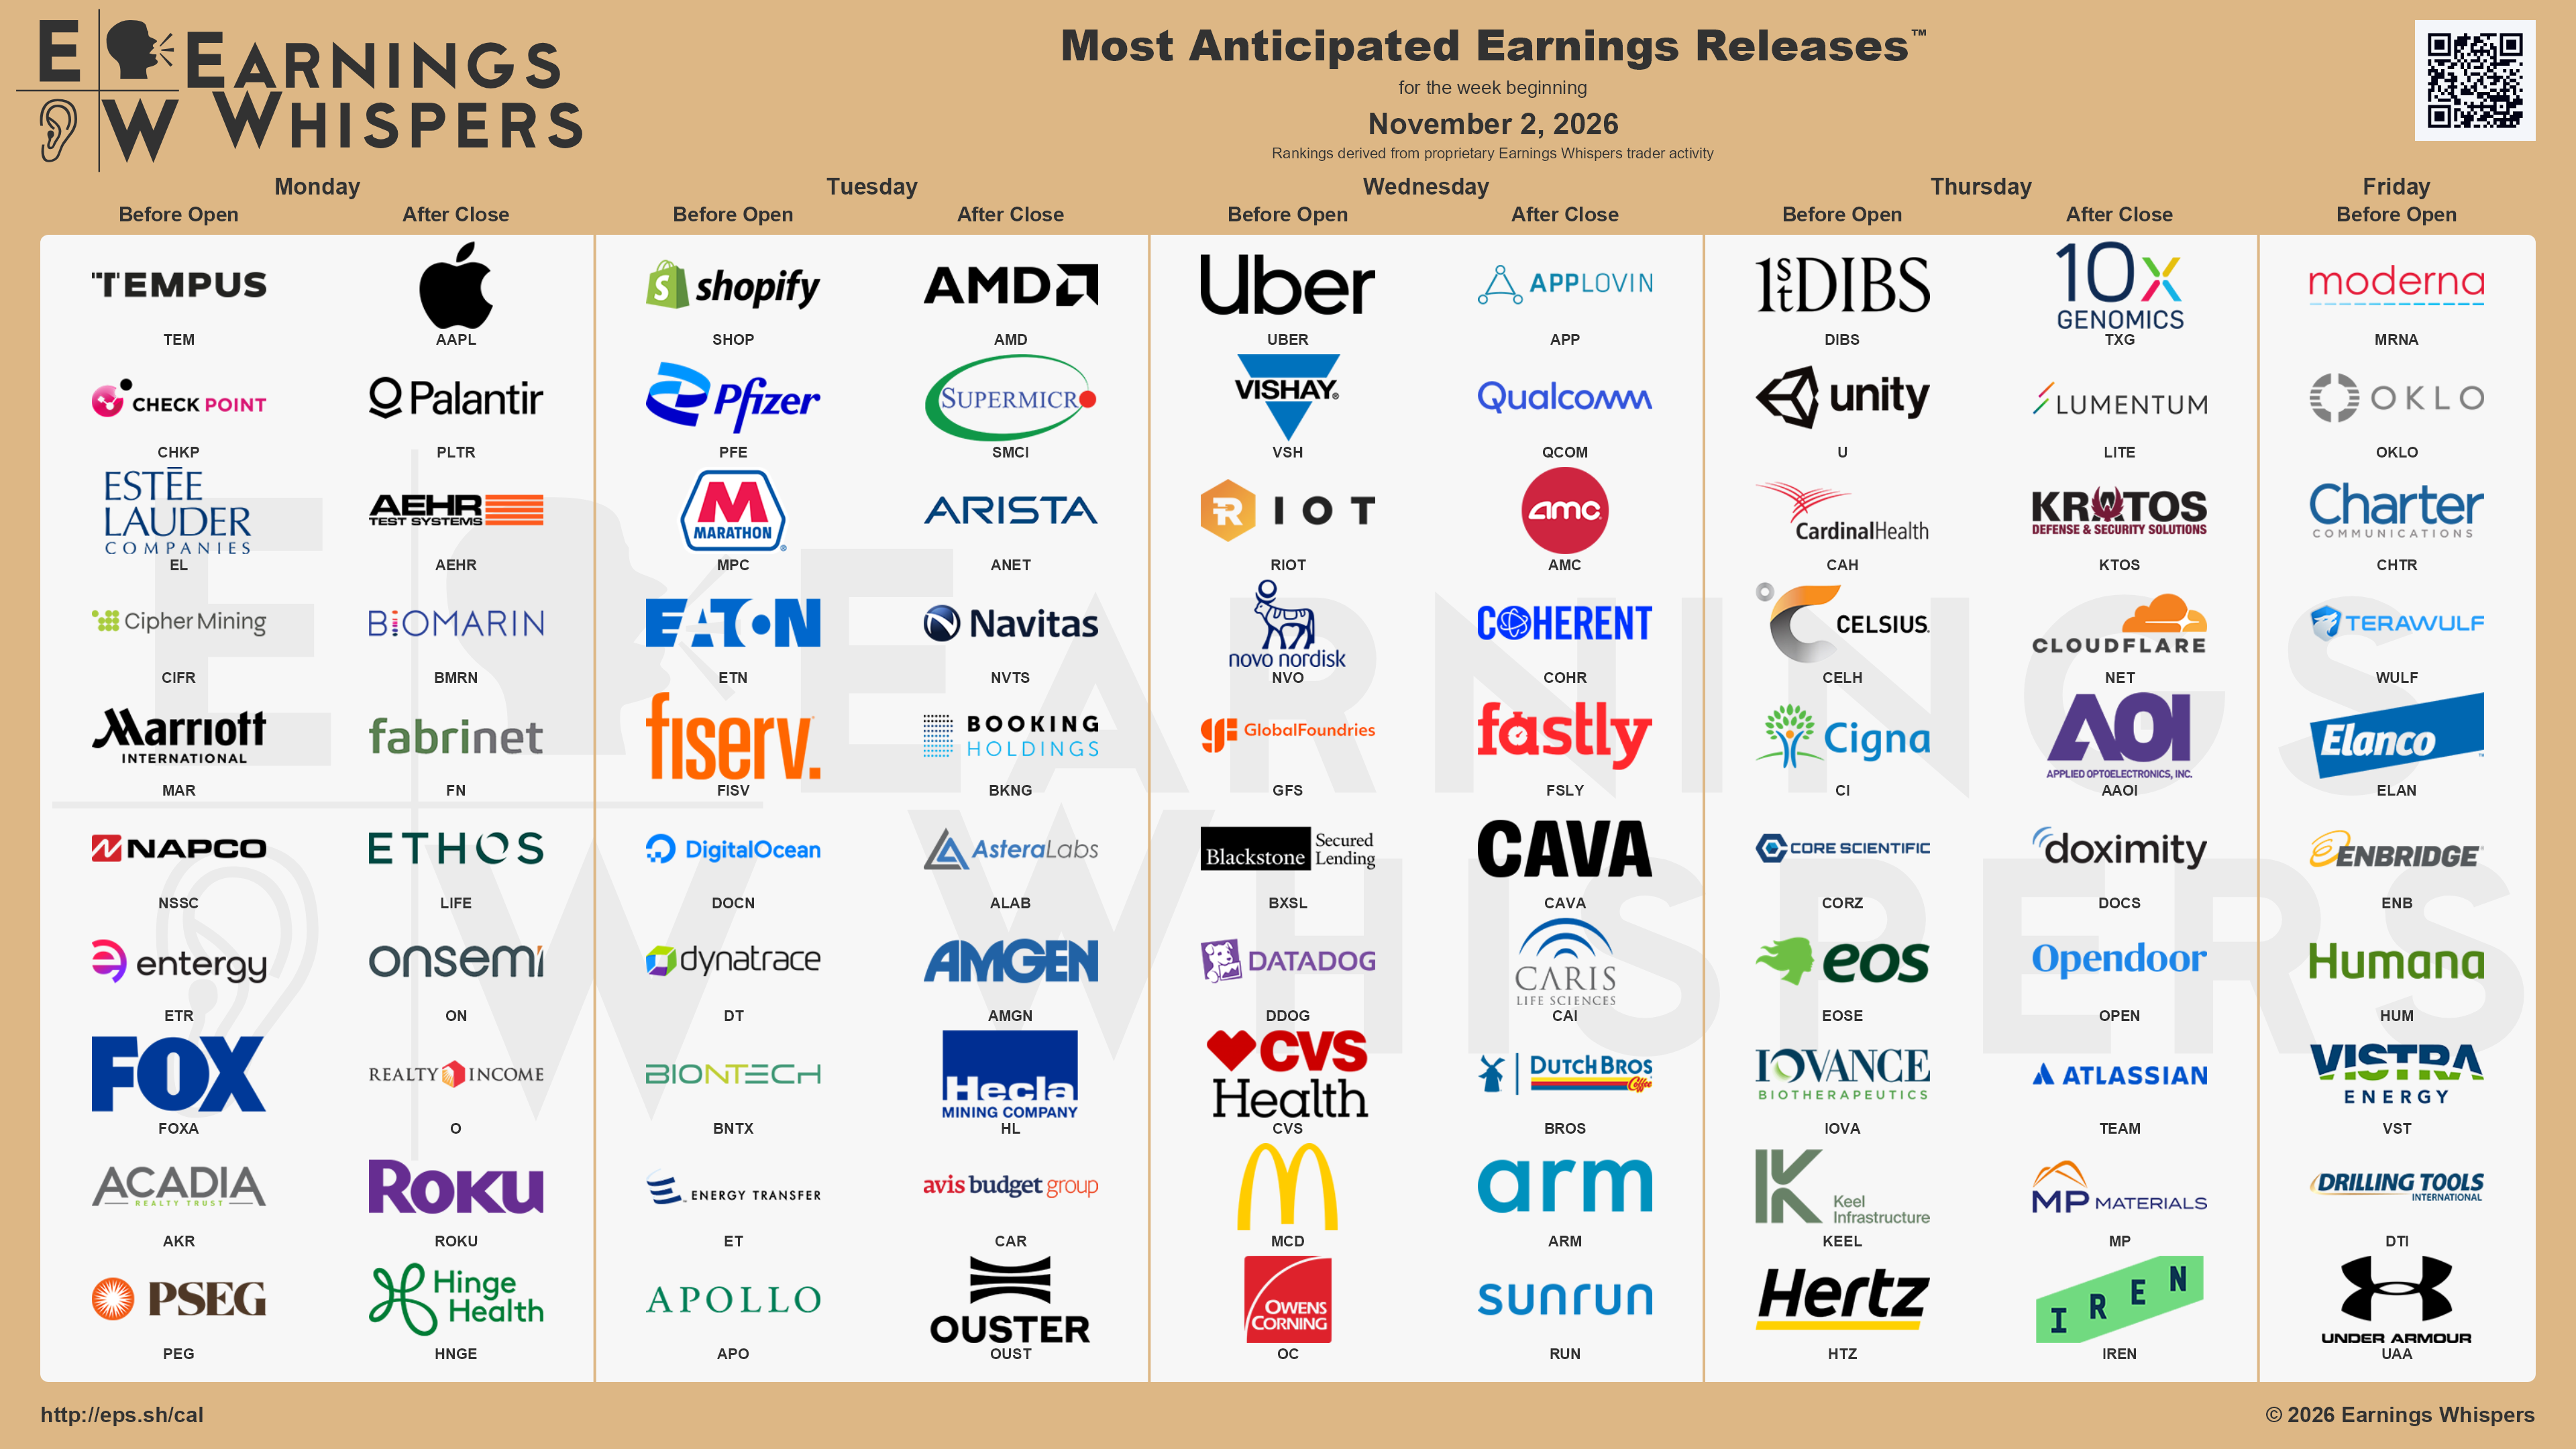
Fox Beat Consensus Estimates
Monday, November 2, 2026 at 8:00 AM
Fox (FOX) reported earnings of $2.54 per share on revenue of $4.57 billion for the fiscal first quarter ended September 2026. The consensus earnings estimate was $2.12 per share on revenue of $4.29 billion. The company beat consensus estimates by 19.81% while revenue grew 22.28% on a year-over-year basis.
Twenty-First Century Fox Inc is a diversified media and entertainment company. It operates in five business segments: Cable Network Programming, Television, Filmed Entertainment, Direct Broadcast Satellite Television, and Other Corporate and Eliminations.
Twenty-First Century Fox Inc is a diversified media and entertainment company. It operates in five business segments: Cable Network Programming, Television, Filmed Entertainment, Direct Broadcast Satellite Television, and Other Corporate and Eliminations.